

Was asked to join Schwab Network to discuss Nvidia earnings.
Below are the two forces at play, plus the 5 areas we focused on…
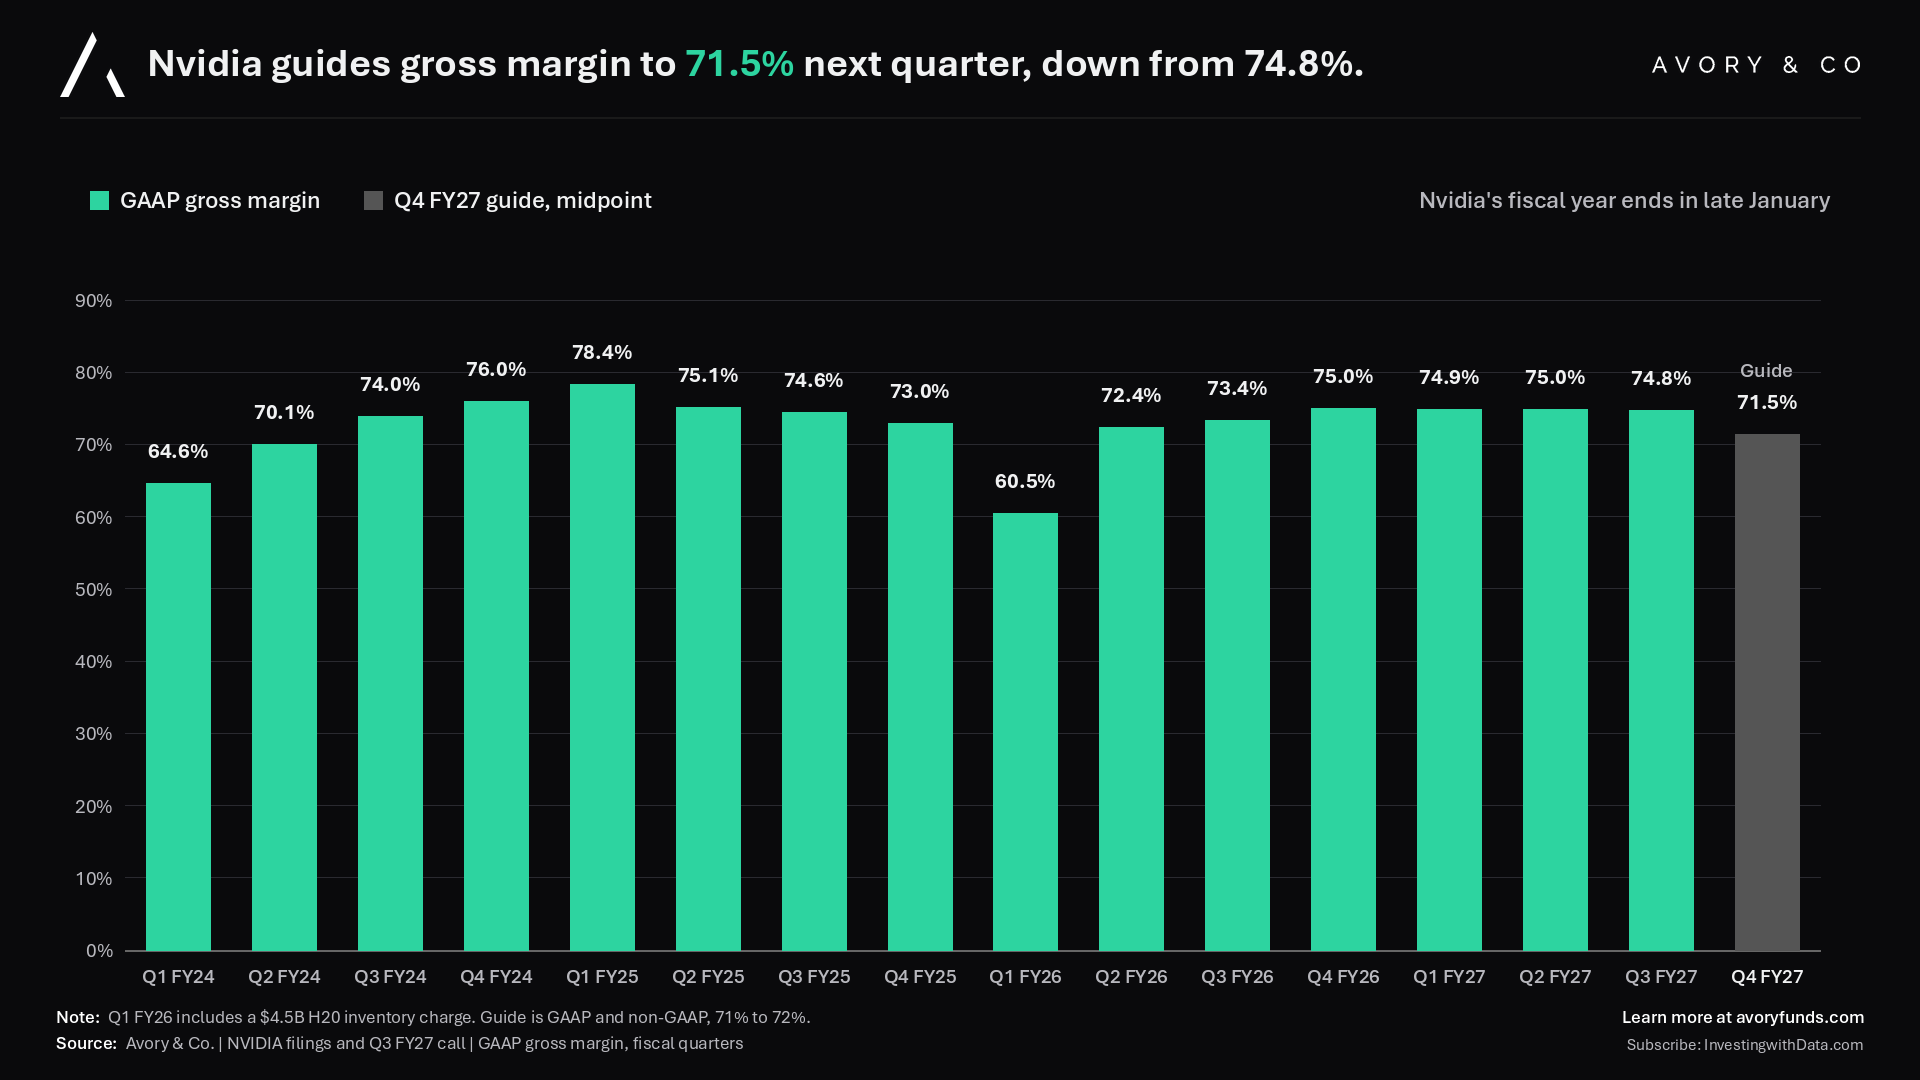
Margins from 79% to a guide of 71.5%…
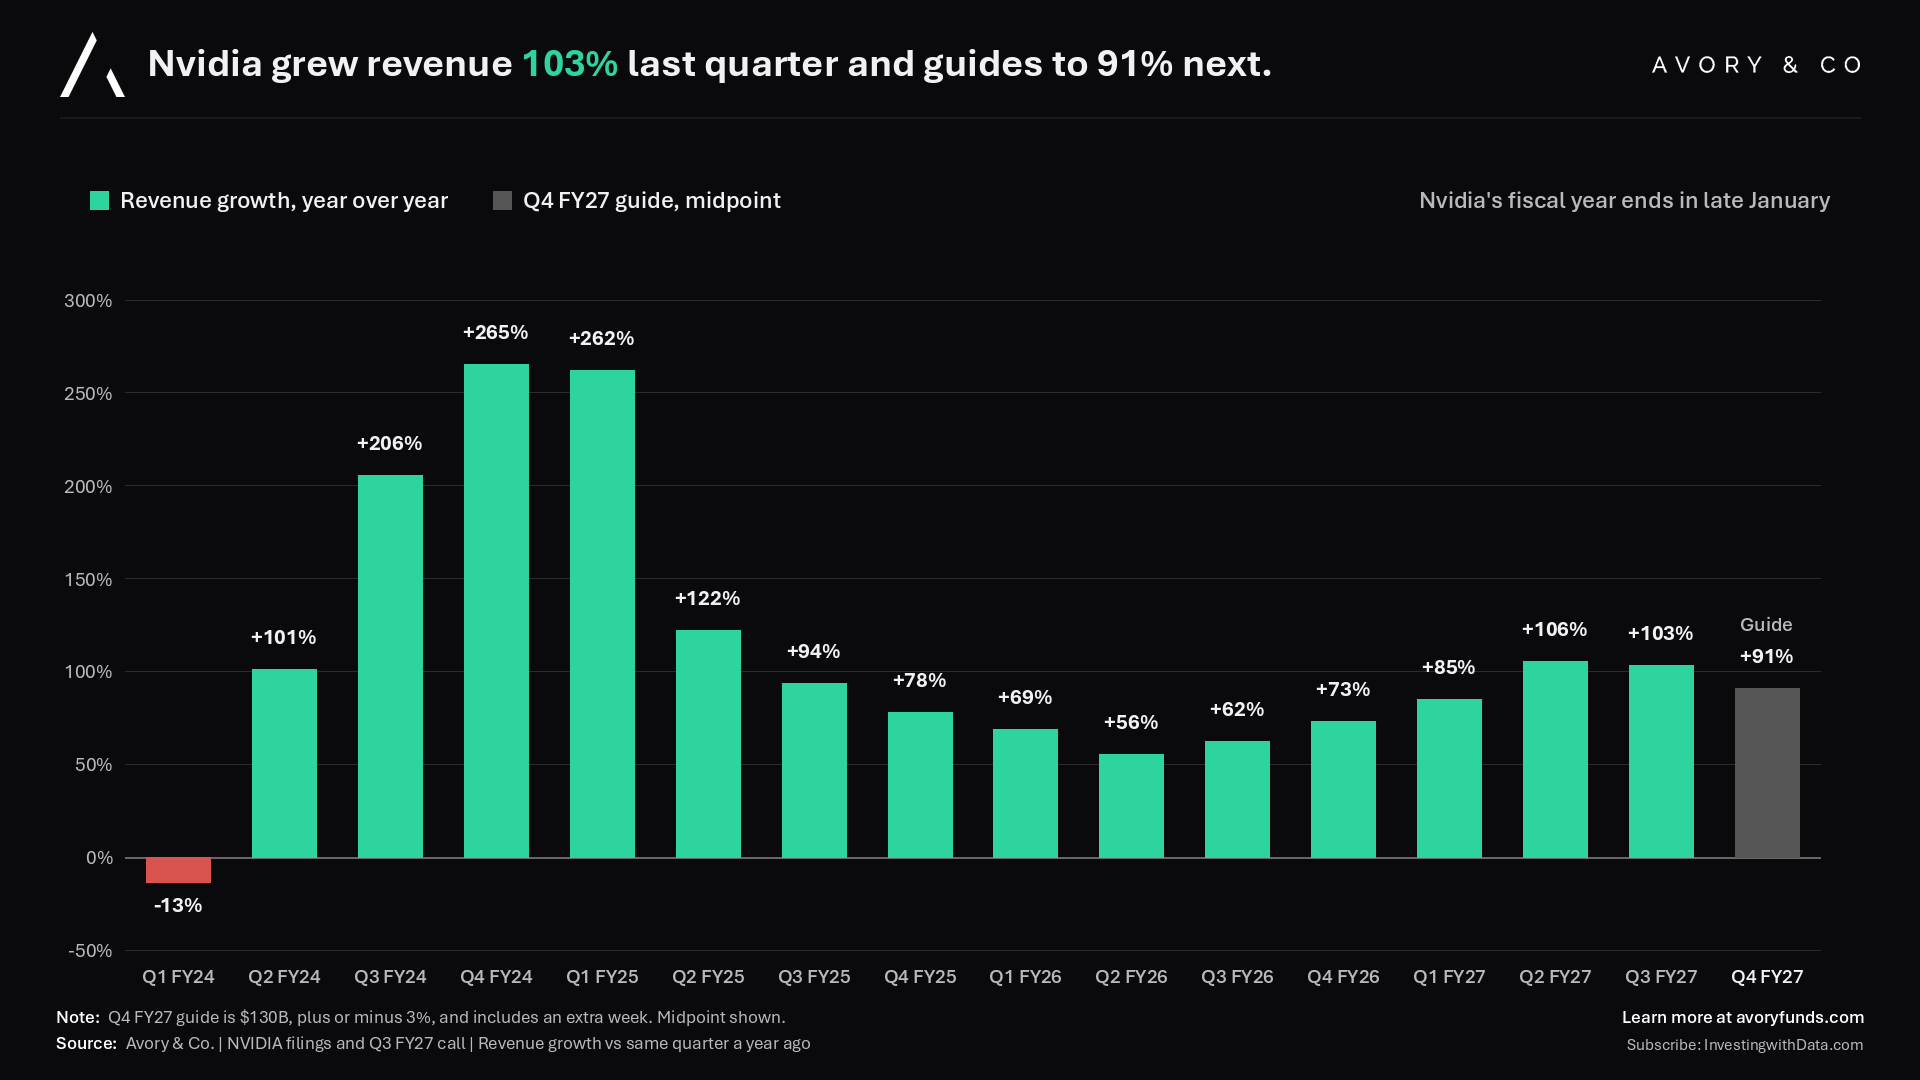
Revenue growth incredible given size BUT it is going from hundreds to 91% to 75% next year…
Markets are fickle, traders trade, we aren’t traders so to us these numbers are incredible.
We had 5 main areas we were focused on
Leadership: Jensen’s potential return ruled out. Focus shifts to succession, execution, and retaining NVIDIA’s innovative culture.
Growth: Exceptional quarter. Revenue +103% to $115.8B; $130B guided next quarter. Demand remains strong.
Diversification: Networking now a $20B+ quarterly business. Vera Rubin expands the platform. Hyperscaler mix down from 69% to 56% year over year.
Margins: Peak 78.9% in 2024, now 74.9%, guiding 71–72%. Three AI investment cycles: absolute spending, spending growth rates, and ultimately returns on the buildout.
Ecosystem: NVIDIA remains exceptionally positioned and committed to supporting AI infrastructure partners. Financing discipline and returns across the ecosystem will be increasingly important.